Ever heard the term “table stakes” and wondered what it really means? You’re not alone — it turns up in poker, boardrooms and industry reports, and everyone seems to use it slightly differently.
Knowing what table stakes are helps you understand the basic expectations in any field: the minimum you must offer just to be considered. Read on to learn where the phrase comes from, how it applies in business, and how to make sure you aren’t left behind.
What Does Table Stakes Mean in Business?
In business, “table stakes” are the minimum standards a company must meet simply to participate in a market. They aren’t the extra features that win customers over; they’re the baseline capabilities customers and partners expect as standard.
For example, an online shop needs secure payments and reliable delivery to be taken seriously. Those things won’t make the brand stand out, but without them the business won’t get a fair hearing. Table stakes change as technology and expectations evolve, so what was once optional can become essential quite quickly.
Meeting these basics doesn’t guarantee success — it only clears the hurdle to compete. Once the fundamentals are in place, a company can focus on differentiators that create real advantage.
Origin of the Term Table Stakes
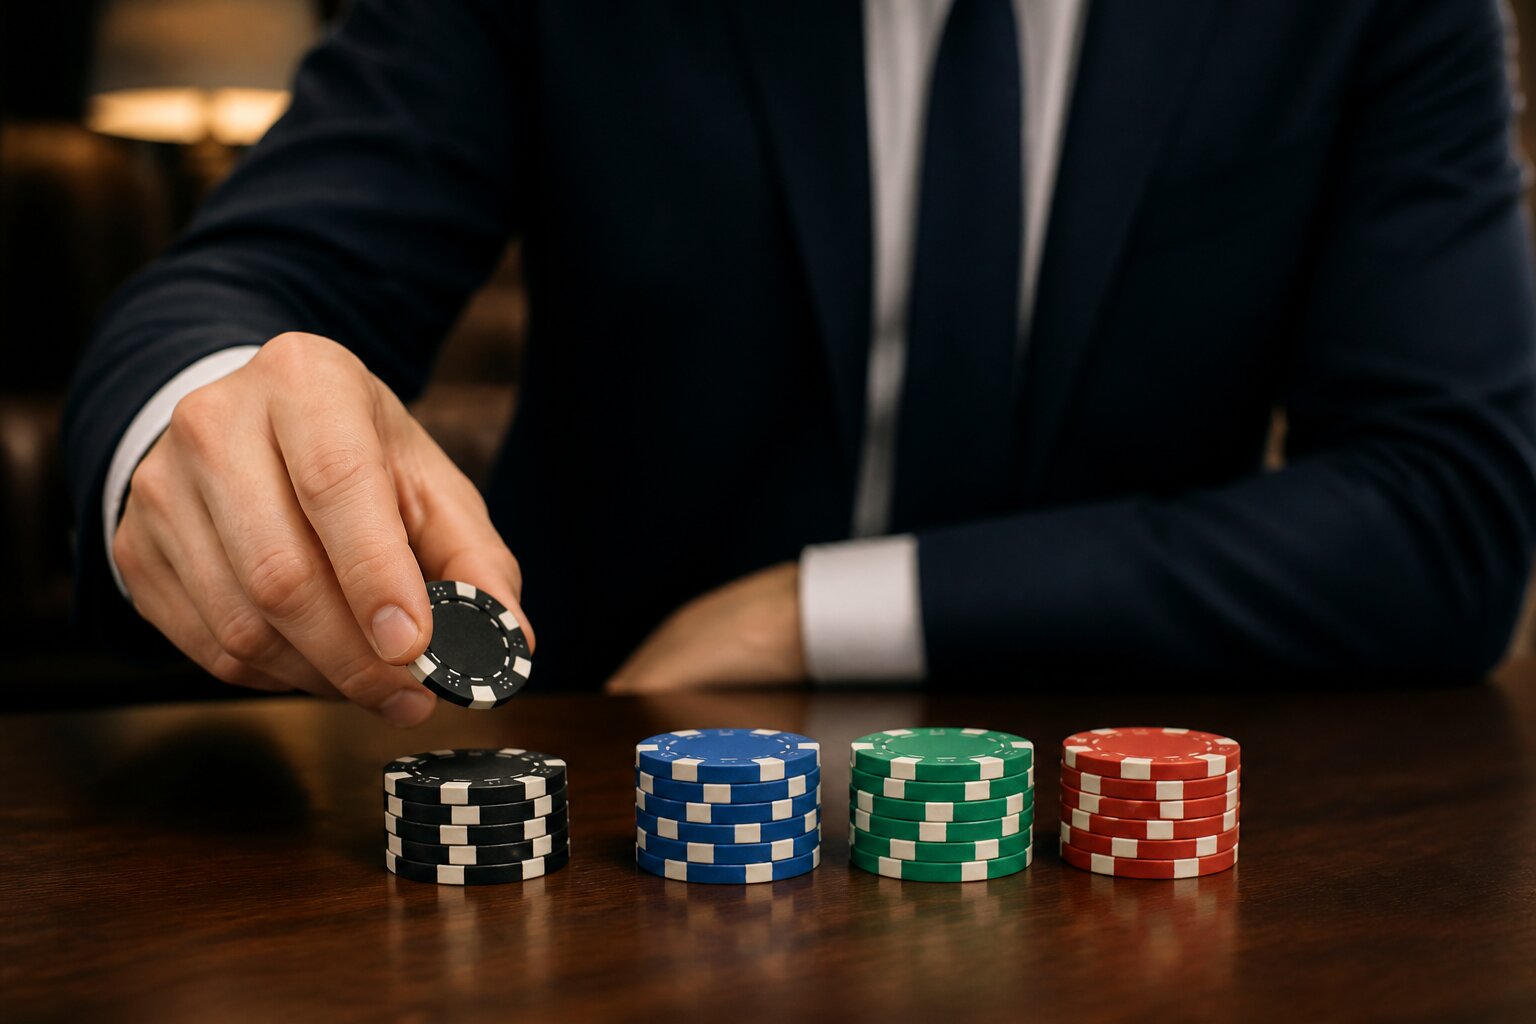
The phrase comes from poker. At a table, players place a set amount of money into play; that amount is their stake for that hand. The rule keeps everyone at the same starting point and prevents players from betting beyond what they have committed at the table.
Business borrowed the image to describe those baseline requirements that keep an organisation “in the game.” It suggests things that must be in place before any attempt is made to gain competitive advantage. Using the metaphor highlights both fairness and the idea that certain expectations are shared across players.
Typical business table stakes include:
- a reliable product or service that meets basic customer needs
- competent staff and operational processes
- basic regulatory and legal compliance
- clear branding and basic digital presence
Thinking in terms of table stakes helps leaders separate foundational investments from those that aim to create additional value. It also reminds organisations that without meeting these basics, efforts to compete on features or innovation may be undermined.
Why Are Table Stakes Important for Companies?
Table stakes set the minimum expectation for quality, safety and legal compliance. They form the baseline that customers, partners and regulators expect before any relationship or transaction can proceed.
They help build trust by showing an organisation meets accepted standards. That trust matters to:
- customers, who expect reliable products and clear recourse when things go wrong
- partners, who need certainty that their own exposure will be limited
- regulators, who require demonstrable compliance to avoid enforcement action
If a company overlooks these basics, it may struggle to win contracts, retain customers or pass audits. Failing to meet table stakes can lead to direct costs such as fines and remediation, and indirect costs such as lost business and damaged reputation.
Conversely, meeting table stakes lets leadership focus on higher-value activity rather than firefighting basic failures. This frees resources to invest in:
- new services and product development
- better customer experience and loyalty-building activities
- strategic innovation that drives growth and competitive advantage
Keeping pace with table stakes also protects reputation and reduces operational risk. When standards shift, for example tighter data protection rules or new safety requirements, adapting promptly signals that an organisation takes its responsibilities seriously and reduces the chance of regulatory, financial or reputational harm. Maintaining these fundamentals also supports staff confidence and smoother day-to-day operations, making it easier to scale and compete.
Common Examples of Table Stakes in Different Industries
Table stakes look different from one sector to another, but they share the same role: enabling an organisation to operate and be considered trustworthy.
Banking
The baseline expectations for banks centre on safety, transparency and compliance. Customers and regulators expect a consistent standard of protection and clarity.
- Secure online access, so customers can log in safely and with appropriate authentication.
- Robust fraud prevention, including transaction monitoring and timely alerts.
- Regulatory compliance, covering reporting, customer due diligence and clear disclosure of fees.
Beyond these foundations, banks must maintain resilient infrastructure to avoid outages and provide straightforward dispute resolution when problems occur.
Technology
For tech firms, fundamentals focus on reliability, security and respectful handling of user data. These basics reflect the reliance people place on digital services and on companies to act responsibly.
- Dependable customer support, with clear channels and reasonable response times.
- Routine security updates, including patching vulnerabilities and monitoring for breaches.
- Sensible data handling, with transparent privacy policies and appropriate data minimisation.
Uptime guarantees and clear terms of service also help users judge whether a provider meets expected standards of performance and trustworthiness.
Retail
In retail, customers expect clear information, fair policies and reliable fulfilment across both physical and online channels. Meeting these basics prevents frustration and protects brand reputation.
- Clear return policies that are easy to find and understand.
- Accurate product information, including descriptions, pricing and stock levels.
- Dependable delivery, with reliable fulfilment, tracking and timely updates.
Good customer service and easy avenues for complaint resolution are additional essentials that help turn a basic transaction into a repeat relationship.
These examples underline that table stakes are about meeting the practical standards customers and regulators regard as necessary for safe and reliable service. Failing to meet them risks loss of trust, regulatory action and damage to an organisation’s ability to compete.
How Do Table Stakes Differ from Competitive Advantages?
Table stakes are the prerequisites of participation; competitive advantages are the features that create preference. Table stakes cover the basic conditions that a business must meet to be taken seriously in a market. They include things like reliable delivery, legal and regulatory compliance, secure systems and consistent quality. Without these, a firm often cannot compete at all.
Competitive advantages sit on top of those basics. They are the elements that make customers favour one provider over another, and they shape long-term loyalty and pricing power.
Once fundamentals are met, firms can invest in additional areas to create real differentiation. Common ways to build competitive advantage include:
- innovation in products or processes
- a distinctive brand identity and messaging
- unique services or customer experiences
That distinction helps explain why two companies with similar table stakes can perform very differently in the market. One may merely meet expectations, while the other exceeds them through clear positioning, smarter execution or a stronger emotional connection with customers.
Signs Your Business Is Behind on Table Stakes
Recognising when you are lagging matters. Typical warning signs include:
- outdated technology, such as slow or unresponsive websites and legacy systems that hinder efficiency
- frequent data-security concerns raised by customers or visible weaknesses in your security controls
- difficulty meeting regulatory obligations, including missed deadlines or insufficient record-keeping
Other indicators to watch for are:
- repeated complaints about service quality, longer resolution times and slipping customer satisfaction scores
- unclear or inconsistent policies that create friction for customers and staff
- partners hesitating to collaborate, withdrawing opportunities or asking for extra assurances
These problems often start small but can compound quickly if not addressed, increasing operational costs and damaging reputation. Left unresolved, minor issues can create gaps that are costly and time-consuming to fix.
Regularly reviewing operations, tracking customer feedback and benchmarking against peers are practical ways to spot gaps early. Specific steps you can take include:
- running periodic technology and security audits
- analysing complaint trends and recovery performance
- comparing key metrics with industry standards to prioritise fixes
Proactive monitoring helps stop small faults becoming serious liabilities and supports steady, compliant improvement.
How Can Organisations Identify Their Table Stakes?
Identifying table stakes begins with understanding stakeholder expectations. Key groups to consider include:
- customers
- regulators
- industry peers
Monitoring regulatory guidance and industry standards reveals what is required to operate legitimately. Organisations should keep a clear record of applicable rules and any recent changes so teams can act quickly when expectations evolve.
Customer feedback often highlights practical needs that should be treated as minimum requirements. Regularly collecting and analysing feedback helps spot recurring issues that indicate a baseline shortfall. Benchmarking services against similar organisations also helps pinpoint where basics are missing and where customers now expect more.
Comparisons should cover both tangible elements, such as service availability and complaint handling, and less visible ones, such as data protection and transparency. Attending sector events or training keeps teams aware of emerging standards and offers opportunities to test assumptions against peers.
This is an ongoing process rather than a one-off checklist. Periodic reviews, simple metrics to measure compliance with core expectations, and a culture that listens to external signals make it easier to adapt when the baseline shifts. Regularly updating policies and sharing findings across the organisation helps ensure table stakes remain current.
What Happens If a Company Ignores Table Stakes?
Ignoring these minimums can lead to tangible consequences. Common immediate impacts include:
- loss of customers
- regulatory penalties
- damage to reputation
Relationships with partners and suppliers may also suffer if basic expectations are not met. That can mean delayed deliveries, reduced collaboration or tougher commercial terms, all of which raise operating costs and weaken resilience.
Over time, failure to meet table stakes makes growth harder. It becomes increasingly difficult to win new contracts, to attract and keep talent, or to secure favourable financing. Recovering trust with customers, partners and regulators is often slow and expensive.
Addressing fundamentals early prevents these downstream problems and preserves strategic options. Investing in the basics protects competitiveness and keeps choices open as the business scales.
Table Stakes Myth-Busting: Common Misconceptions
Several misunderstandings about table stakes can steer decision-making off course. It helps to call out the common myths so teams do not over- or under-invest in basics.
Common misconceptions include:
- Believing that meeting table stakes guarantees success. Meeting them allows a product or service to participate in the market, but it does not deliver competitive advantage or long-term growth.
- Thinking table stakes never change. They evolve as customer habits, technology and regulation shift, so what sufficed last year may not be enough today.
- Assuming table stakes are uniform across all markets. Requirements differ by industry and jurisdiction, so what is adequate in one context may be inadequate elsewhere.
- Treating table stakes as optional rather than foundational. Skimping on fundamentals can create risks and costs that outweigh any short-term savings.
Recognising the variability of table stakes across sectors and regions is important. Organisations should assess requirements against local rules, customer expectations and the competitive landscape rather than relying on a one-size-fits-all checklist.
Clearing up these myths helps organisations focus attention where it matters: keeping the basics current, managing compliance and risk, and reserving resources to build genuine differentiation that customers will notice.
Key Takeaways on Table Stakes
Here are the main points to keep front of mind when thinking about table stakes.
- Table stakes are the minimum standards required to participate in a market, shaped by customer expectations and legal obligations.
- They don’t create advantage but are essential to be considered credible and compliant.
- Because they evolve, regular review and benchmarking are necessary to stay current.
- Practical steps to identify them include listening to customers, monitoring regulation and comparing with peers.
By treating table stakes as the foundation rather than the finish line, organisations preserve trust, reduce risk and free up resources to build genuine competitive strengths.
**The information provided in this blog is intended for educational purposes and should not be construed as betting advice or a guarantee of success. Always gamble responsibly.